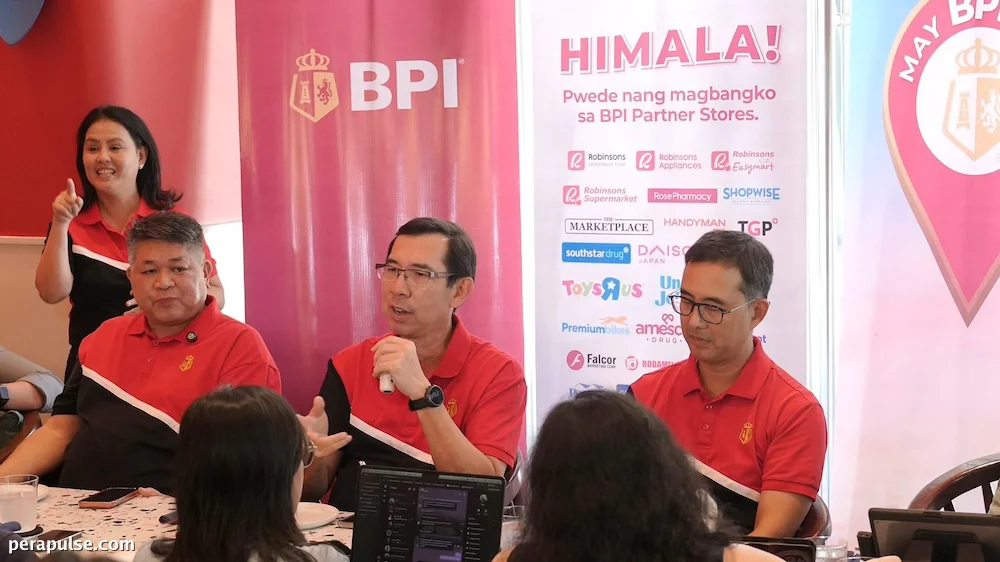
Starting July 1, 2026, the Bank of the Philippine Islands (BPI) will no longer charge fees for transfers made through InstaPay and PESONet. This decision eliminates the previous P10 fee for interbank transfers, a move that may force other banks to reevaluate their own fee structures.
Impact of BSP Regulations
The BSP circular states that you cannot have one sector subsidize the other. The difference in pricing should reflect only the network fee.
TG Limcaoco, BPI President and CEO
BPI's elimination of transfer fees comes in alignment with the Bangko Sentral ng Pilipinas (BSP) Circular No. 1238. This regulation aims to ensure that banks justify their fees based solely on operational costs, rather than using one type of transfer to subsidize another.
- BPI's fee change could lead to a domino effect among other banks.
- Customers may increasingly prefer banks that offer free transfers.
- BPI aims to enhance customer engagement and loyalty through this strategy.
Historically, banks have defended transfer fees by citing costs associated with digital transactions, which Limcaoco estimated at around P22 each. However, he believes that these costs remain consistent whether a transfer is made internally or externally.
Challenges for Competitors
With BPI setting the precedent for free transfers, competitors now face the challenge of justifying their existing fees. Limcaoco suggests that banks can either align with BPI’s model or risk losing customers to more competitive platforms.
Moreover, BPI's decision could have implications for e-wallet services like GCash, which many Filipinos currently use as their primary payment method. Limcaoco expressed concern that customers might prefer to move funds from their bank to GCash, thus bypassing BPI’s ecosystem.
As the Philippine banking landscape evolves, BPI's move may encourage other banks to rethink their fee structures. The implications of these changes will likely be significant, not only for banks but also for customers seeking more cost-effective banking solutions.